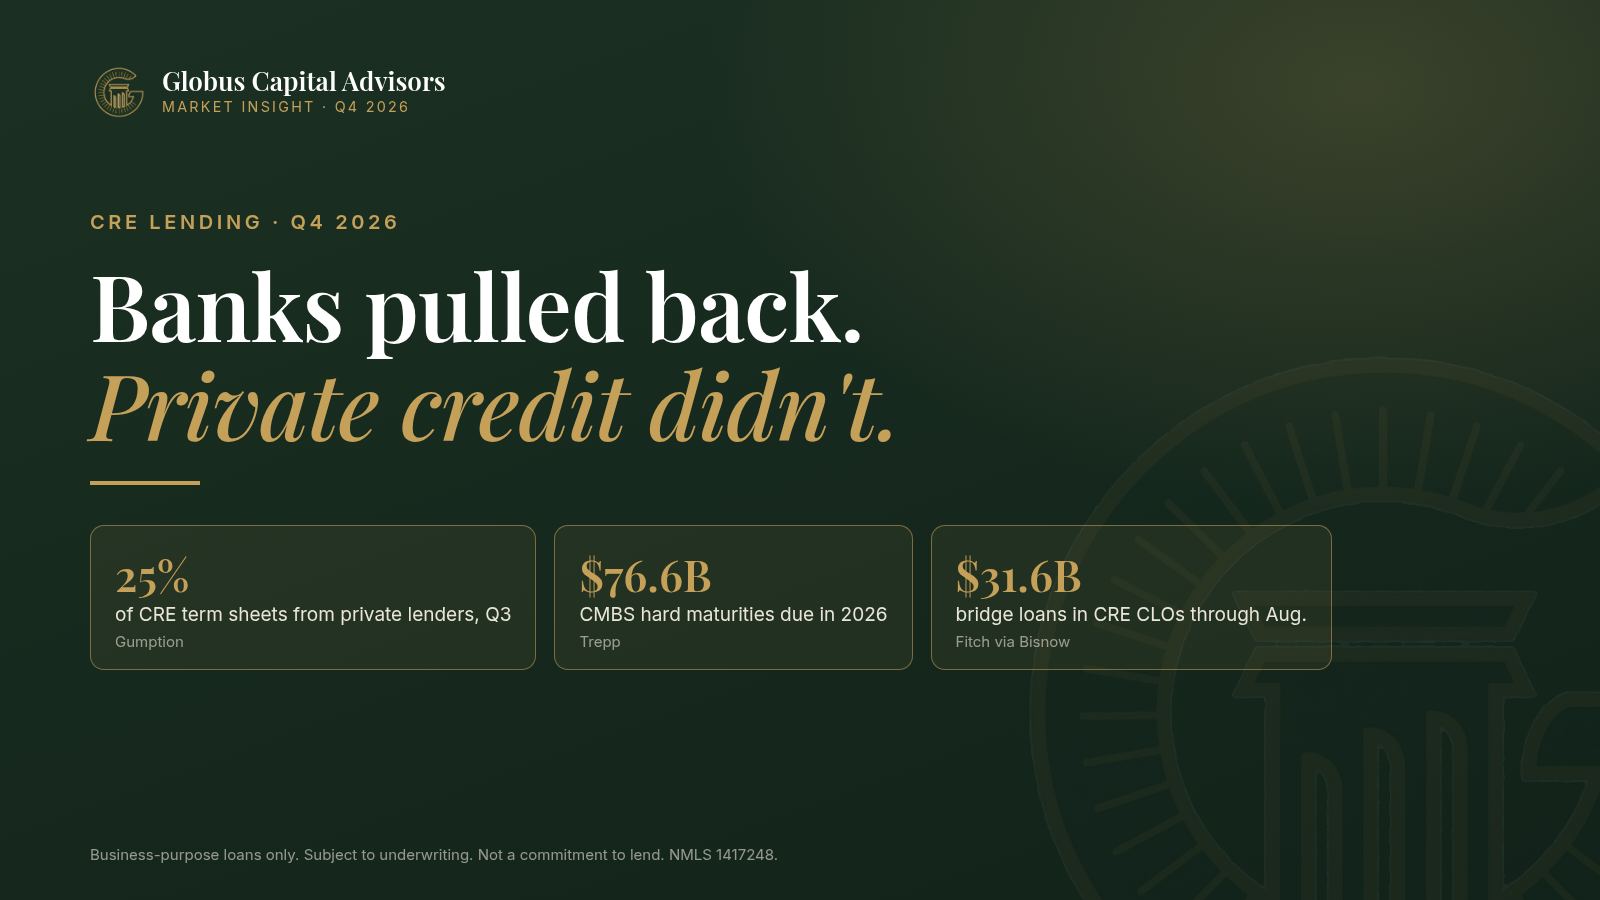
In one quarter, private lenders went from writing about 1 in 8 commercial real estate term sheets to 1 in 4. That's from Gumption's Q3 2026 lending report (Gumption). And it's happening right as the market enters its heaviest stretch of loan maturities in years.
If you own, buy or build investment property, the lender that funded your last deal may not fund your next one. Here's what's changing in commercial and DSCR lending heading into Q4 2026, backed by the data.
1. The refinancing wall is back-loaded, and Q4 is the heavy part
Trepp counts $76.6 billion in CMBS hard maturities due in 2026, more than either of the prior two years. 39% of that lands in Q4 alone (Trepp).
October's cohort by itself is $4.70 billion, up from $2.74 billion in September. 27.74% of that balance has a debt yield below 6.0%, which Trepp classifies as severely impaired. Office makes up the biggest share of October maturities. But most of the stress is now in multifamily (51.86% of the impaired balance) and hospitality (31.90%) (Trepp).
Trepp also found that 36% of 2026 maturities carry a debt yield of 8% or less. That's the group most likely to run into trouble refinancing.
Pull quote: "39% of 2026's $76.6B in CMBS hard maturities fall in Q4 alone." (Trepp)
2. "Bridge-to-bridge" is buying time, not solving the problem
Many owners can't get permanent financing, so they're rolling one floating-rate bridge loan into another. CRE CLO issuers securitized $31.6 billion of bridge loans through August, more than in all of 2025, according to Fitch data reported by Bisnow.
Delinquencies look fine for now: just 0.52% of Fitch-rated loans were seriously delinquent in July. But part of that is because lenders keep rewriting terms. Modified loans are up 68.6% since the end of 2025, to nearly $4 billion (Bisnow/Fitch).
The same report notes that the 10-year Treasury is up more than a full point this year. That's why rate relief hasn't reached long-term CRE debt.
On pricing, PeerSense's tracking of $10M+ bridge loans shows terms of 12 to 36 months and a tracked ceiling of about 73% maximum LTV as of Oct. 2 (PeerSense).
Pull quote: "Modified CRE CLO loans are up 68.6% since the end of 2025." (Fitch via Bisnow)
Facing a 2026 or 2027 maturity? Globus Capital Advisors connects you with lenders for bridge financing to acquire, reposition, lease up or recapitalize a property before permanent debt. Get financing for your deal →
3. Private credit is filling the gap banks left, at a price
Gumption's platform data shows how quickly the mix of lenders has changed (Gumption):
- Private lenders issued 25% of term sheets in Q3 2026, up from 13% in Q2.
- Private pricing has held at roughly 300 bps over conventional.
- In construction lending, private lenders issued half of all term sheets, up from about a quarter.
- Banks and credit unions cut their highest construction LTC from 85% to 75%. Private lenders came in at a median 82.5% LTC, compared with 70% for conventional lenders.
- Private construction pricing rose during the quarter, while conventional construction pricing held flat.
MSCI data reported by GlobeSt shows the same trend. Investor-driven lenders, including debt funds, grew to 16% of commercial property lending in the first half of 2026, up from 13%, with an average LTV of 69.5%, the highest of any lender group MSCI tracks (via Bisnow).
What this means: leverage is still available, but it costs more. Lender selection now affects your returns as much as rate does.
Pull quote: "Private lenders now write half of all CRE construction term sheets, up from a quarter last quarter." (Gumption)
4. DSCR loans: more competition, tighter spreads
On the investor side, business-purpose DSCR loans have become the main driver of non-agency growth:
- Investor and DSCR loans made up 35.1% of non-agency production in August 2026, up from 28% a year earlier (Optimal Blue via National Mortgage Professional and HousingWire).
- DSCR and investor lock volume is up 130% from January 2022 to August 2026 (Optimal Blue via HousingWire).
- Bank of America Securities projects $175B in non-agency originations in 2026, up from $108B in 2025. DSCR and investor loans account for about half of collateral (HousingWire).
- DSCR rates are now about 50 bps over 30-year conventional rates, down from 75–100 bps a year ago, according to Kiavi's Charles Goodwin (NMP).
There's a catch. When rate sheets look alike, lenders compete on reserves, DSCR floors, how they calculate rent, and closing speed. HousingWire also reports that fraud risk indicators now fire on 1 in 44 investment-property applications. That makes a well-documented file more valuable.
Pull quote: "DSCR spreads have compressed to ~50 bps over conventional, from 75–100 bps a year ago." (Kiavi's Charles Goodwin via NMP)
Screen your rental deal before you shop it. Our free playbook shows how to run a fast, AI-assisted DSCR screen on rent rolls and T-12s so you can spot coverage problems before a lender does. Read the AI-Assisted DSCR Screening playbook →
5. What to do with this now
LakeRock's October briefing recommends that owners reprice near-term maturities using current lender quotes, then recalculate DSCR, debt yield and refinance proceeds. They should also document where any required paydown or fresh equity will come from (LakeRock). Based on the sources above, a practical checklist:
- 1. Know your gap. Compare what your property's NOI supports at today's rates with your payoff.
- 2. Name the takeout before you take the bridge. Bridge-to-bridge is a strategy for buying time, not for exiting.
- 3. Price across lender types. With private credit about 300 bps over conventional (Gumption), the cheapest leverage and the most leverage often come from different lenders.
- 4. Document everything. As DSCR lending gets more crowded and fraud screening tightens, clean files close faster.
The bottom line
The refinancing wall isn't a crash. It's a sorting process. Assets with real cash flow and well-prepared sponsors are getting financed, often by private and non-bank capital. Assets with thin debt yields are buying time. Q4 2026 will show which group your deal is in.
Have a deal that needs a lender? Submit it to Globus Capital Advisors →
Disclosures
Craig Kaminski, NMLS 1417248. Globus Capital Advisors is not a lender or a licensed entity. Business-purpose commercial financing only; subject to lender underwriting; not a commitment to lend.